
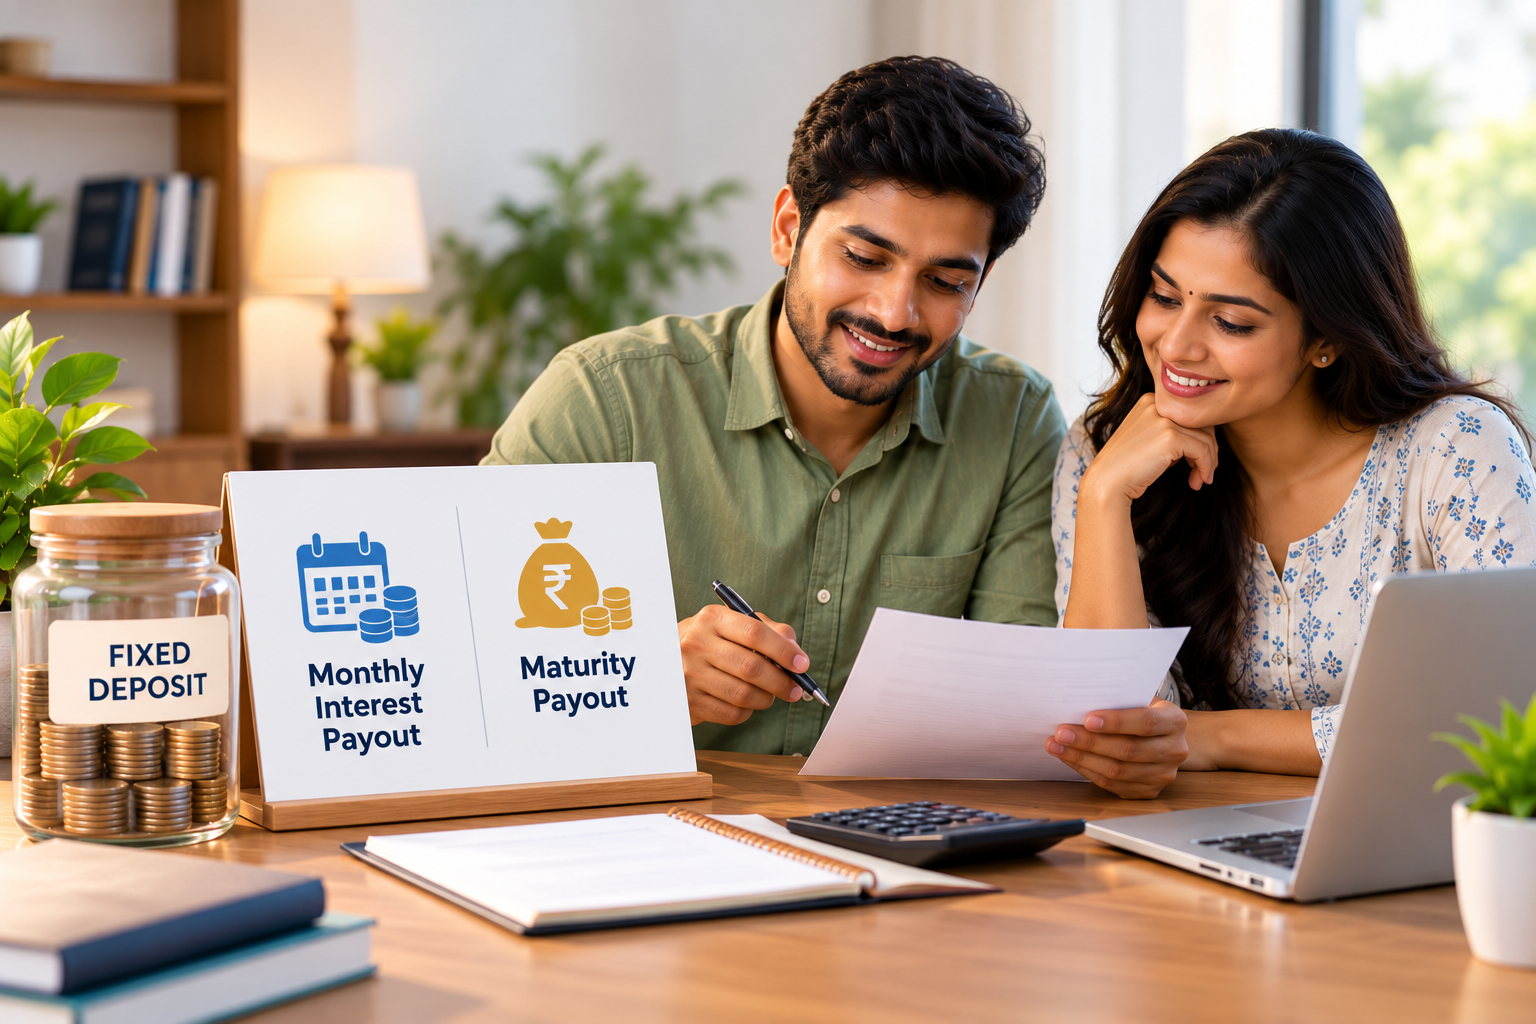
A Fixed Deposit (FD) is a savings option for individuals who want to set aside a lump sum for a specific period and earn interest according to the applicable deposit terms. While most people compare interest rates and deposit tenures before opening an FD, another important decision is often overlooked: Should you receive your interest every month or wait until the deposit matures?
Both options can serve different financial needs. Monthly interest payouts may help individuals manage recurring expenses, while maturity payouts may suit those saving towards a future financial goal.
Understanding how these options work can help you choose a Fixed Deposit that aligns with your income requirements, financial commitments, and savings plans.
What Is a Fixed Deposit Interest Payout?
A Fixed Deposit interest payout refers to when the interest earned on your deposit is paid to you.
Depending on the scheme, deposit holders may have different interest payout options, including:
-
Monthly interest payout: Interest is paid at regular monthly intervals.
-
Annual interest payout: Interest is paid once every year.
-
Maturity interest payout: Interest is paid when the Fixed Deposit reaches its maturity date.
Each option has its own advantages depending on how and when you want to use the interest earned.
The appropriate choice depends on whether you need periodic income or prefer receiving the interest at the end of the deposit tenure.
How Does a Monthly Interest Fixed Deposit Work?
A monthly interest Fixed Deposit is designed for individuals who prefer receiving interest periodically rather than waiting until maturity.
When you choose this option, the applicable interest is paid monthly according to the deposit scheme's terms.
For example, someone with a lump sum available for deposit may want to use the monthly interest towards regular household expenses without withdrawing the principal amount.
Monthly interest payouts may be useful for:
-
Retired individuals seeking supplementary income
-
Families managing recurring expenses
-
Individuals who want predictable periodic cash flow
-
Members who prefer receiving interest regularly
-
People planning additional income for everyday financial needs
However, the principal amount generally remains deposited for the selected tenure, subject to the scheme's withdrawal conditions.
It is also important to understand that the actual monthly payout depends on the deposit amount, applicable interest rate, calculation method, and other scheme conditions.
What Is a Fixed Deposit Maturity Payout?
A maturity payout is an option where the interest is paid at the end of the selected deposit tenure.
Instead of receiving interest every month, the depositor waits until maturity to receive the amount payable under the scheme.
This option may suit individuals who do not require periodic income and want to keep their savings allocated towards a future financial requirement.
For example, a person saving for a planned family function, major purchase, or another financial milestone may prefer receiving the deposit proceeds at a specific future date.
A maturity payout can help with:
-
Planning future financial commitments
-
Saving towards a specific milestone
-
Keeping funds allocated to a long-term objective
-
Avoiding the temptation to spend periodic interest payments
-
Receiving the applicable interest at the end of the tenure
Whether interest is compounded or calculated on a simple-interest basis depends on the particular deposit scheme. A maturity payout should not automatically be assumed to provide higher returns.
Monthly Interest vs Maturity Payout: Key Differences
Understanding the differences between these two options can make the selection process easier.
| Factor | Monthly Interest Payout | Maturity Payout |
|---|---|---|
| Interest payment | Every month | At maturity |
| Main purpose | Periodic income | Future financial goal |
| Cash flow | Regular interest payments | Payment at the end |
| Suitable for | Individuals needing monthly income | Individuals planning a future expense |
| Spending flexibility | Interest available periodically | Interest retained until maturity |
| Returns | Based on scheme terms | Based on scheme terms |
Neither option is universally better.
The most suitable choice depends on your financial requirements and the terms of the Fixed Deposit.
When Should You Choose a Monthly Interest Payout?
A monthly interest payout may be worth considering when you want to receive interest regularly.
For example, retired individuals may prefer periodic interest payments to supplement their existing income.
Similarly, someone managing household commitments may find regular interest payouts more convenient than receiving the entire interest amount at maturity.
Before choosing this option, consider whether the expected payout will meaningfully support your expenses.
It is also important to understand that monthly interest payouts are not equivalent to a salary or guaranteed replacement for regular employment income. The amount depends on the applicable deposit terms, and the safety of the deposited principal depends on the financial institution and relevant protections.
When Should You Choose a Maturity Payout?
A maturity payout may be more appropriate when your main objective is to accumulate funds for a future requirement.
For instance, you may be planning a significant purchase or preparing for a family milestone.
If you do not need regular interest payments, receiving the applicable interest at maturity may help you keep the deposit aligned with your financial goal.
Before selecting this option, check the maturity date, interest calculation method, applicable rates, and withdrawal conditions.
How Does Deposit Tenure Influence Your Decision?
The tenure of your Fixed Deposit is another important factor when selecting an interest payout option.
A shorter tenure may suit a financial requirement expected in the near future, while a longer tenure may align with a goal planned several years ahead.
However, choosing a longer tenure means committing your funds for an extended period, subject to the applicable withdrawal rules.
Before finalising the tenure, consider:
-
When you are likely to need the deposited amount.
-
Whether you require interest payments during the deposit period.
-
How much money you can comfortably keep deposited.
-
Whether premature withdrawal is permitted.
-
The applicable interest rate and payment conditions.
Selecting a tenure based on your actual financial needs can help you avoid unnecessary changes to your deposit later.
Does the Interest Payout Option Affect Your Returns?
The interest payout option can affect the timing and amount of interest received.
In some deposit schemes, interest paid at maturity may benefit from compounding, whereas periodic payout schemes distribute interest rather than retaining it for reinvestment.
However, this depends on the interest calculation method and the conditions of the particular scheme.
For this reason, it is important to compare the actual interest payable under each available option rather than assuming one will always generate higher returns.
Before opening an FD, request details of the applicable interest rate, payment frequency, calculation method, and total expected payout.
Consider Your Emergency Financial Requirements
Before placing a substantial amount into a Fixed Deposit, consider whether you have sufficient funds available for unexpected expenses.
Medical needs, household repairs, family responsibilities, or temporary changes in income can arise without warning.
Keeping a separate emergency fund can reduce the likelihood of needing to withdraw your Fixed Deposit prematurely.
If early withdrawal is permitted, understand whether penalties, reduced interest rates, or other conditions apply.
Financial flexibility should remain an important part of your savings plan.
Understand the Tax Implications of FD Interest
Interest earned from Fixed Deposits may be subject to income tax under applicable rules.
The timing of interest payments does not necessarily determine when the income becomes taxable.
Tax deduction at source may also apply depending on the nature of the institution, applicable provisions, and the depositor's circumstances.
Before selecting an interest payout option, understand the relevant tax treatment and seek professional guidance where necessary.
Explore Fixed Deposit Options at Pride Credit Society
Pride Credit Society provides Fixed Deposit facilities for eligible active members, with different tenure and interest payout options.
The society's Fixed Deposit facility includes options for receiving interest monthly, annually, or at maturity, subject to the applicable scheme conditions.
Members can explore the available deposit tenures, interest rates, eligibility requirements, and documentation procedures before making a decision.
For more information, visit the Pride Credit Society Fixed Deposit page.
Before placing funds, members should also understand the society's regulatory status, financial position, applicable deposit protection arrangements, and the risks associated with the deposit. Co-operative society deposits should not automatically be assumed to have the same protections as deposits with DICGC-insured banks.
How to Choose the Right Fixed Deposit Interest Payout Option
Choosing between monthly interest and maturity payouts begins with understanding your financial priorities.
If you need supplementary monthly cash flow, a periodic interest payout may be more appropriate.
If you are saving towards a future expense and do not require regular interest payments, a maturity payout may better suit your objective.
Consider the following before deciding:
-
Your regular income and monthly expenses
-
Your future financial commitments
-
The amount available for deposit
-
The selected deposit tenure
-
Applicable interest rates and calculation methods
-
Premature withdrawal conditions
-
Tax implications and deposit-related risks
Reviewing these factors can help you make a more informed decision rather than selecting a scheme based only on the advertised interest rate.
Make Your Fixed Deposit Work Towards Your Financial Goals
A Fixed Deposit can be a useful component of a planned savings strategy when its tenure, interest payout structure, and associated risks match your financial circumstances.
Monthly interest payouts may suit individuals seeking periodic income, while maturity payouts may be appropriate for those preparing for future financial requirements.
The right choice depends on when you need the money, how you intend to use the interest, and whether the deposit terms align with your savings objectives.
For eligible members exploring Fixed Deposit options, Pride Credit Society offers different interest payout choices and deposit tenures, subject to applicable conditions.
Review the latest Fixed Deposit terms and consult your nearest Member Service Centre before making a decision.
Plan your savings and future financial goals with Pride Credit Society.

